The Psychology of Money: How Identity Shapes Financial Decisions
We often think we make financial decisions with numbers. But numbers enter a mind that already has a history. Explore how identity, upbringing, scarcity, status and belonging shape our relationship with money—and what it means to build a healthier financial identity.
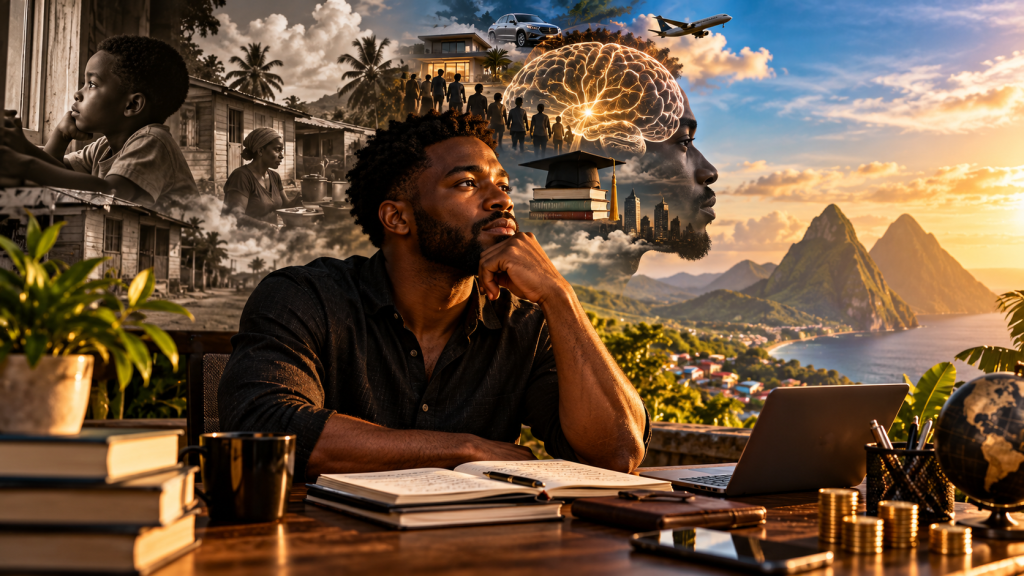
We often speak about money as though it were primarily a mathematical problem.
Earn more than you spend.
Save consistently.
Avoid unnecessary debt.
Invest for the future.
Understand compound interest.
On paper, much of personal finance can appear remarkably straightforward.
Human beings are not.
Numbers enter a mind that already has a history.
Before you ever opened an investment account, applied for a loan, negotiated a salary or built a budget, you had already been learning what money meant.
You watched adults respond to bills.
You noticed who seemed to have money and who did not.
You heard conversations about rich people, poor people, debt, success, security and struggle.
Perhaps money was discussed openly in your home.
Perhaps it was surrounded by silence.
Perhaps spending meant celebration.
Perhaps saving meant safety.
Perhaps wealth was admired.
Perhaps it was treated with suspicion.
Long before money became something you managed, it became something you interpreted.
And those interpretations can quietly become part of identity.
You Were Learning About Money Before You Knew You Were Learning
Research into financial socialization gives us useful language for something many people understand intuitively.
Families do not only teach children about money through formal lessons.
They teach through behaviour.
Through conversation.
Through what is celebrated.
Through what produces conflict.
Through what children observe when groceries are bought, bills arrive, somebody loses a job, somebody receives a raise or an unexpected expense appears.
A broad review of financial-socialization research found that parental modelling, parent-child financial discussion and direct experiences with money are associated with later financial attitudes, knowledge, behaviour and wellbeing.
This does not mean childhood permanently determines your financial future.
It means none of us begins from a psychologically neutral position.
We arrive in adulthood carrying stories.
Some are useful.
Some were formed under circumstances that no longer exist.
Some were inherited from people doing the best they could with what they knew.
And some continue influencing decisions long after we have forgotten where they came from.
Read the research review on family financial socialization
Money Is Never Only Money
A dollar has a numerical value.
Psychologically, however, money can represent many things at once.
Security.
Freedom.
Status.
Love.
Control.
Independence.
Belonging.
Escape.
Proof.
This helps explain why two people earning similar incomes can behave very differently.
One may experience saving as security.
Another may experience the same act as deprivation.
One person may see an expensive purchase as unnecessary.
Another may see it as evidence that years of sacrifice finally meant something.
One entrepreneur may be comfortable charging appropriately for valuable work.
Another may repeatedly underprice themselves even while knowing, intellectually, that the business cannot survive that way.
The spreadsheet sees numbers.
The human being sees meaning.
That distinction matters.
The Identity We Are Trying to Protect
Sometimes a financial decision makes little sense until we understand the identity underneath it.
Imagine someone who grew up feeling visibly poorer than the people around them.
Years later, when their income improves, consumption may carry a meaning far beyond the object being purchased.
The car may not simply be transportation.
It may mean:
I am no longer the person who had less.
The designer clothing may not simply be clothing.
It may mean:
I finally belong in rooms where I once felt invisible.
This does not make the purchase automatically foolish.
Nor should every act of consumption be reduced to insecurity.
People are allowed to enjoy what they earn.
The deeper question is whether we understand what we are actually buying.
Sometimes we are purchasing an object.
Sometimes we are purchasing a feeling about ourselves.
Knowing the difference creates choice.
Scarcity Changes the Way We Think
There is another mistake we should avoid.
We should not turn every financial difficulty into a character judgment.
It is easy to look at somebody struggling financially and conclude that they simply need greater discipline.
Sometimes they do.
But scarcity itself can affect decision-making.
When money is chronically insufficient, the mind must devote enormous attention to immediate trade-offs.
Which bill can wait?
How long can the car continue making that sound?
Can groceries stretch another three days?
Can this expense be postponed until payday?
What happens if the child gets sick?
Research on the psychology of scarcity has explored how persistent shortage can consume mental bandwidth and make already difficult decisions harder.
This complicates the easy language of financial self-help.
It is difficult to think about a retirement account twenty years away when today’s electricity bill is due.
It is difficult to optimize investment returns when the immediate problem is unstable income.
This does not remove personal agency.
It places agency inside reality.
Read more about the psychology of scarcity
The Caribbean Knows Something About Scarcity
This conversation has particular resonance in the Caribbean.
Across the region, many families have developed sophisticated cultures of survival.
People stretch salaries.
Relatives abroad send support home.
A single household may help finance several generations at once.
Someone with a stable income may quietly become the emergency fund for an extended family.
Parents make sacrifices so children can study.
People build homes slowly, sometimes over many years, adding another section when money becomes available.
Informal networks often perform functions that formal financial systems do not.
These practices contain intelligence.
They also shape identity.
A person raised in an environment where money could disappear quickly may continue holding cash long after their circumstances become more secure.
Someone who watched parents struggle may become intensely risk-averse.
Another person may respond in the opposite direction, determined to enjoy money immediately because tomorrow has never felt guaranteed.
Neither reaction can be understood completely by looking only at a bank statement.
History is present in the transaction.
Sometimes Income Changes Before Identity Does
This is one of the more interesting financial transitions.
A person can begin earning considerably more money while still thinking from the conditions in which they previously lived.
Sometimes this produces caution.
The person earns more but remains terrified of losing everything.
Sometimes it produces consumption.
The person finally has access to things they were previously denied and feels compelled to demonstrate that their circumstances have changed.
Sometimes it produces guilt.
They begin doing better financially than friends or relatives and feel uncomfortable moving too far from the identity of the group.
Sometimes it produces responsibility.
Increased income attracts increased expectations from everyone around them.
This is why earning more does not automatically create a healthy relationship with money.
Income can change faster than identity.
And if identity never catches up, a person may unconsciously recreate familiar financial conditions even after their external circumstances improve.
The Price of Belonging
Money decisions also occur socially.
We rarely decide what is “enough” in complete isolation.
We look sideways.
At friends.
At neighbours.
At colleagues.
At people online.
At the lifestyles associated with whatever group we believe we have entered—or hope to enter.
This creates a peculiar problem.
As income rises, the reference group can rise with it.
The person who once dreamed of simply being comfortable may eventually feel unsuccessful because they are comparing themselves with people operating at an entirely different level of wealth.
Enough keeps moving.
And when enough has no definition, money has no natural stopping point.
There will always be somebody with more.
More income.
More property.
More status.
More visible success.
A financial life built entirely through comparison can therefore become psychologically unwinnable.
Financial Literacy Is Necessary, but It Is Not the Whole Answer
None of this is an argument against financial education.
People should understand interest.
Debt.
Investing.
Risk.
Taxes.
Insurance.
Asset ownership.
Cash flow.
The difference between consumption and investment.
These things matter enormously.
But information has limits.
A person can know that they should save and still repeatedly spend.
They can understand investing and remain too afraid to begin.
They can know that debt is becoming dangerous while continuing to use it to sustain a lifestyle tied to identity.
They can understand that their work is underpriced and still feel deeply uncomfortable asking for more.
At that point, the problem is no longer simply:
What do I know about money?
Another question becomes necessary:
What does money mean to me?
The Financial Self You Are Becoming
Identity is not fixed.
That may be the most hopeful part of this conversation.
You can inherit a financial story without being required to repeat it.
You can honour the people who raised you without reproducing every belief they held about money.
You can come from scarcity and learn stewardship.
You can come from abundance and learn restraint.
You can learn to earn without making income the measure of your worth.
You can learn to enjoy money without needing consumption to prove that you matter.
You can become generous without destroying your own financial foundation.
You can build wealth without believing wealth makes you more human than someone who has less.
You can become financially ambitious without becoming spiritually owned by money.
This is not accomplished through positive thinking alone.
It requires knowledge.
Practice.
Better systems.
Better opportunities.
Honest reflection.
And sometimes the uncomfortable recognition that a behaviour we have been calling financial is actually emotional.
Ask Better Questions About Your Money
Before the next important financial decision, it may be useful to become curious about the person making it.
What am I afraid will happen if I do not spend this money?
What am I afraid will happen if I do?
Am I buying usefulness, pleasure, status, relief or belonging?
What did the people who raised me teach me about wealthy people?
What did they teach me about debt?
About risk?
About asking for more?
About owning things?
About investing?
About what someone like us is supposed to be able to achieve?
Which of those beliefs remain useful?
Which belong to circumstances that have changed?
Which have I never examined at all?
These questions do not replace a budget.
They may help explain why you keep abandoning one.
The Inner Economy and the Outer Economy
Perhaps the psychology of money becomes clearest when we stop forcing a choice between personal responsibility and external reality.
Both matter.
The economy around you matters.
Your income matters.
The cost of living matters.
Opportunity matters.
Education matters.
Access to capital matters.
Family responsibilities matter.
The financial circumstances into which you were born matter.
A person earning barely enough to cover basic expenses is operating within a different set of choices from someone whose income comfortably exceeds their needs.
We should not pretend otherwise.
But there is also an economy within.
The beliefs through which we interpret opportunity.
The fears through which we interpret risk.
The identity through which we interpret success.
The emotional history through which we interpret security.
Two people can encounter similar opportunities and respond differently because opportunity is never interpreted by numbers alone.
One sees possibility.
Another sees danger.
One believes they are capable of learning what they do not yet understand.
Another quietly assumes that investing, business ownership or wealth belongs to a category of people they have never imagined themselves becoming.
This is why neither extreme is sufficient.
We cannot reduce every financial struggle to mindset.
And we cannot reduce every financial outcome to circumstance.
The more useful question is how the two interact.
What circumstances are actually limiting me?
And what limitations have I continued carrying internally even after circumstances changed?
Knowing the difference is part of financial maturity.
Money as a Tool, Not a Mirror
Perhaps one of the healthiest shifts we can make is learning to stop asking money to tell us who we are.
Your bank balance contains information.
It does not contain your human value.
Your income contains information.
It does not measure the depth of your character.
Your possessions reveal some of your choices.
They cannot tell us whether your life is meaningful.
Money is extraordinarily useful.
It can create options.
Buy time.
Reduce certain forms of stress.
Fund education.
Support family.
Build businesses.
Acquire assets.
Finance art.
Preserve institutions.
Create experiences.
Help another person survive a difficult season.
Build something that continues after you.
Money is powerful precisely because it can be directed.
But when money becomes a mirror through which we constantly ask whether we are successful, worthy or enough, the tool begins governing the person holding it.
A Different Kind of Financial Freedom
Financial freedom is usually described numerically.
A certain amount invested.
A certain level of passive income.
A certain net worth.
Those definitions can be useful.
But perhaps there is another dimension.
Financial freedom may also mean reaching a point where money no longer has to perform your identity for you.
Where you can earn without needing income to prove your importance.
Spend without needing purchases to prove your arrival.
Save without allowing fear to make you incapable of living.
Invest without pretending risk has disappeared.
Give without abandoning yourself.
Build wealth without becoming possessed by the need for more.
And make financial decisions from a clearer understanding of both the world around you and the person within you.
Because perhaps the deepest financial question is not simply:
How much money do I have?
It is:
Who am I becoming in my relationship with it?
Continue the Exploration
If this essay has made you think differently about wealth, identity and the beliefs beneath financial behaviour, these books from the ThaPoetic1 library continue the conversation from different directions.
The Prosperity Parable: Secrets of Wealth, Wisdom & Legacy
A natural next read for this conversation, The Prosperity Parable approaches prosperity through story, wisdom and the longer relationship between wealth and legacy. It is for readers interested not merely in accumulating more, but in thinking more carefully about what prosperity is meant to serve.
Explore The Prosperity Parable →
The Codex of Repentance: A Unified Theory of Love, Success, and Wealth
For readers drawn to the deeper relationship between inner transformation and outer results, The Codex of Repentance widens the conversation beyond money itself—toward success, wealth, responsibility and the beliefs from which a life is constructed.
Explore The Codex of Repentance →
Mastering the Law of Attraction: A Practical Guide to Manifesting Your Dreams
If your interest lies especially in mindset, intention and the relationship between thought and deliberate action, Mastering the Law of Attraction offers another doorway into the inner side of creation and personal change.
Explore Mastering the Law of Attraction →
Wealth begins in the material world of income, assets, ownership and opportunity.
But our relationship with those things is always mediated by the person we have become.
Understanding both may be where a more conscious form of prosperity begins.